- Who is liable when someone is hurt on a NYC sidewalk?
- Does a typical homeowner's policy cover sidewalk injuries?
- What if someone is injured while I'm waiting on a repair?
- Can an open sidewalk violation affect my coverage or premiums?
- What should I ask my insurer right now?
- How do I protect myself while a defect is still there?
- FAQ
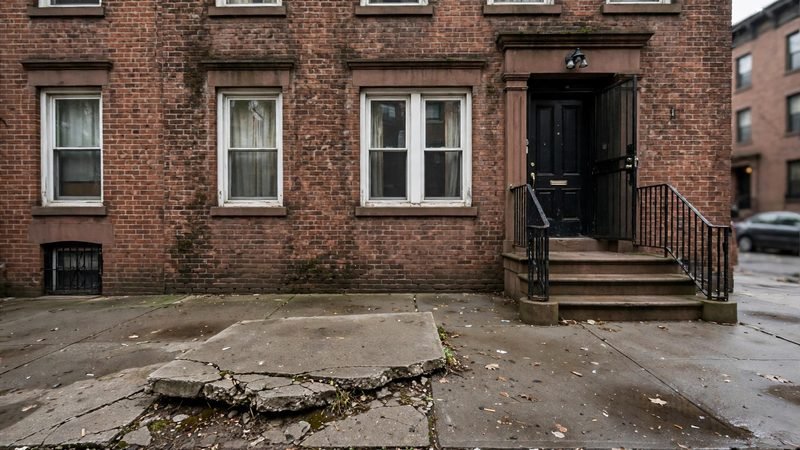
Often, yes. A typical homeowner's policy includes liability coverage that can pay when someone is injured on your sidewalk and you're legally responsible, up to your policy limit. But insurers only pay when you were actually negligent, coverage varies by policy, and an open violation or repair delay can complicate a claim. Check your own policy.
Who is liable when someone is hurt on a NYC sidewalk?
In most cases, you are. Under NYC Administrative Code section 7-210, the owner of the property next to the sidewalk must keep it in reasonably safe condition. If someone is injured because you failed to do that, the owner is liable. This has been the rule since the law took effect on September 14, 2003, shifting sidewalk liability from the city to property owners.
There is one important exception. If your property is a one-, two-, or three-family home that you live in (at least in part) and it is used only as a residence, the city generally remains responsible for the sidewalk in front of it. A home with a store on the ground floor or an extra rental unit does not qualify. Everyone else, from brownstone landlords to commercial building owners, carries the duty themselves.
Note that you don't need to own the sidewalk for the liability to fall on you. The sidewalk is usually city land, but maintenance and liability are the abutting owner's problem under 7-210. That is also why the city isn't the one who gets sued for most sidewalk falls: the code expressly says the city is not liable when the injury came from an owner's failure to maintain.
Does a typical homeowner's policy cover sidewalk injuries?
Usually, the injury claim goes to the liability section of the owner's policy. The description below is general information about how these policies work, not a reading of your policy. Homeowner's liability coverage is designed to pay when the homeowner is legally responsible for someone's injury, and a NYC personal injury guide explains that this can include medical expenses, lost wages, and pain and suffering, up to the policy's limits. Standard policies commonly carry liability limits between $100,000 and $300,000, though some owners buy extra umbrella coverage. Many policies also include medical payments coverage (MedPay), which can cover small medical bills without proving fault, usually with limits of $1,000 to $5,000.
The key condition is negligence. The insurer generally pays only if the owner knew or should have known about the dangerous condition and failed to fix it or warn about it. That is what lawyers call actual or constructive notice: a cracked flag you've walked past for months is a harder case for you than a break caused by a truck the day before. If nobody can show you were negligent, the liability coverage doesn't respond.
One more thing worth knowing: New York law actually expects covered owners to be insured. Section 7-211 of the Administrative Code requires property owners subject to 7-210 to carry personal injury and property damage liability insurance. And if an injured person can't find you liable under the small-home exception, their claim is against the city, which has strict deadlines (a notice of claim within 90 days).
What if someone is injured while I'm waiting on a repair?
This is the question that keeps owners up at night, and it came up word for word on a Brooklyn homeowner forum: "Someone gets injured while I'm waiting on repair, will insurance cover it?" The uncomfortable answer is that it depends, and the waiting period itself is part of what makes a claim stronger against you.
Remember the notice rule from above. A defect you know about, especially one the city has already flagged with a violation, is much easier for an injured person to tie to your negligence. The violation notice is official proof that you were told the sidewalk was defective. That doesn't mean your insurer automatically denies the claim, but it does mean the injured person's case against you is stronger, and your insurer will examine your repair timeline closely.
This is also why repair delays are risky in a second way. New York law gives an injured pedestrian three years to sue a private owner, so the fact that you "were getting around to it" doesn't expire as an argument. If you have an open violation, the repair clock is already running: you get 75 days from the notice to finish the repair. Document every step you take toward fixing the defect, including contractor calls, quotes, and permit applications, so you can show your effort if a claim ever comes.
Can an open sidewalk violation affect my coverage or premiums?
Here is where the owner grapevine gets loud, and you should read it carefully. On a Brooklyn homeowner forum, one owner wrote that an outstanding violation can "nullify" a homeowner's insurance policy. That is an unverified owner report, not a rule. Policies and insurers differ, and I could not verify that any insurer voids coverage over a violation as a matter of standard practice.
What is plausible, based on how insurance works, is subtler. Insurers price risk. A known, unrepaired hazard on your property can be used by an insurer at renewal to raise your premium, add an exclusion, or in some cases decline to renew. And when a claim does come in, an adjuster will look at whether the defect was known and left unrepaired, which feeds into whether negligence is established.
The practical takeaway: don't treat the forum claim as fact, but do treat an open violation as a risk signal to your insurer. Clearing a DOT violation and keeping a paper trail of the repair protects you on both the legal and insurance sides.
What should I ask my insurer right now?
You don't need to wait for an accident to get clarity. Call your insurer or agent and ask plain-language questions:
- Does my liability coverage extend to injuries on the sidewalk in front of my property?
- What are my liability limits, and is an umbrella policy worth considering?
- Is there a MedPay limit I should know about?
- Do I need to notify you when I receive a sidewalk violation?
- Are there policy exclusions that apply to unrepaired hazards or code violations?
- If someone is injured, how fast do I need to report it, and what documentation do you want?
Get the answers in writing where you can. If your agent's answers raise concerns, that is the time to compare policies, not after a claim.
How do I protect myself while a defect is still there?
While the defect exists, your job is to shrink both the chance of an injury and the strength of any claim against you.
Start by documenting the defect: dated photos from a pedestrian's eye level, a ruler or coin next to the crack for scale, and notes on when you first noticed it. Fix it as fast as you can; line up a contractor and learn what sidewalk repairs typically cost so you can act rather than stall on sticker shock. If tree roots are involved, check whether the city's Trees and Sidewalks program applies to your property.
Keep a folder with everything: the violation notice, contractor quotes, permit receipts, and photos of the completed repair. If who's actually responsible for the repairs is unclear because of tenants, a managing agent, or a shared driveway, sort that out in writing now, not after a fall. And if someone does get hurt, notify your insurer promptly and don't discuss fault with the injured person, as NYC injury attorneys advise.
Not sure whether a violation is already on file for your property? Run your address through the free lookup tool to check the city's violation and inspection records before you call your insurer. And if you want the basics on the 75-day repair clock and what happens after you get a notice, start there.
FAQ
Does homeowner's insurance pay for the sidewalk repair itself?
Generally, no. Liability coverage is for injury and damage claims by others, not for routine maintenance or repairs the city orders you to make. You pay for the repair; the insurance is there for the injury claim. For help with the repair bill, see what sidewalk repairs typically cost and what happens if the city does the work.
What is NYC Administrative Code 7-210?
It's the law that makes the owner of the property next to a sidewalk responsible for keeping it reasonably safe, and liable for injuries caused by failing to do so. It took effect on September 14, 2003, and covers cracks, raised flags, holes, and uncleared snow and ice.
If I live in my one- or two-family home, is the city liable instead?
Often, yes. The law exempts owner-occupied one-, two-, and three-family homes used only as residences. In that case the city is generally the responsible party, but claims against the city face strict rules, including a notice of claim within 90 days and a prior written notice requirement.
Can my insurer deny a sidewalk injury claim because I had an open violation?
An insurer can dispute a claim when it believes you weren't legally liable, but I could not verify that insurers void coverage over an open violation as a general rule. What an open violation clearly does is strengthen the injured person's negligence case against you, because it's official notice you knew about the defect.
Will filing a sidewalk injury claim raise my premiums?
That depends on your insurer and policy. Insurers can adjust premiums or non-renew based on risk, and a claim history plus an unrepaired hazard gives them reason to look closely. Ask your agent how your policy treats premises-liability claims.
What if the person who fell was partly at fault?
New York follows pure comparative negligence, which means the injured person's own share of fault reduces their recovery but doesn't bar it. For example, if they were distracted, their award is cut by their percentage of fault, not eliminated.
How long does someone have to sue after a sidewalk injury in NYC?
For a claim against a private owner, generally three years from the injury. Claims against the city are much shorter: a notice of claim within 90 days and a lawsuit within one year and 90 days.
What should I do right after someone is hurt on my sidewalk?
Make sure the person gets help, then document the scene: photos of the defect, the date and time, and witness names if any. Notify your insurer as soon as you can, and avoid discussing who was at fault with the injured person. Keep every record of the defect and your repair efforts together.